Can I Finance A Dtg Printer To Build Your Print Business
Yes, you can finance a DTG printer through loans, leases, or equipment financing programs designed for small businesses. DTG printer financing makes it possible to own commercial-grade direct-to-garment printing equipment without paying the full cost upfront. Whether you are launching a print on demand business or expanding an existing shop, the right financing option can keep your business cash flow healthy while you build revenue.
Starting a print business is exciting. You get to create custom t-shirts, hoodies, and all kinds of apparel. But there is one big question standing in your way: how do you pay for the equipment? A DTG printer is not cheap. Most people cannot just pull the full amount out of pocket.
That is exactly why DTG printer financing exists. Whether you are a complete beginner or an experienced printer looking to upgrade, you have options. Can I finance a DTG printer? The short answer is yes. The longer answer is that the right financing path depends on your budget, credit, and business goals. In this guide, we will walk you through every option so you can make a smart decision.
The print on demand industry is growing fast. More people are starting small t-shirt printing businesses from home. And with good reason — the market for custom apparel keeps expanding. But you need the right garment printing equipment to compete. Financing lets you get that equipment now and pay for it over time. Let us dive into how this works.
Key Takeaways
- Multiple financing options exist: You can choose from equipment loans, leases, SBA loans, and retailer financing plans.
- DTG printer costs vary widely: Entry-level machines start around $5,000 while industrial units can exceed $50,000.
- Leasing preserves cash flow: Monthly payments are often lower than loan payments, freeing up money for supplies and marketing.
- Your credit score matters: A strong credit profile unlocks better interest rates and more financing choices.
- Write a solid business plan: Lenders want to see your print business strategy before approving any equipment financing.
- Compare offers carefully: Always review total cost of ownership, not just monthly payments.
📑 Table of Contents
- Understanding DTG Printer Costs
- Can I Finance A Dtg Printer? Yes, Here Are Your Options
- How To Choose The Right Financing Option
- Pros and Cons of Financing a DTG Printer
- Common Mistakes To Avoid When Financing a DTG Printer
- Tips To Get Approved For DTG Printer Financing
- Financing Alternatives To Consider
- What Happens After You Finance Your DTG Printer
- Final Thoughts: Taking The Leap With DTG Printer Financing
Understanding DTG Printer Costs
Before you look at financing, you need to understand what you are paying for. DTG printer cost varies a lot depending on the model and features. Let us break it down so you know what to expect.
Entry-Level DTG Printers
Entry-level machines are perfect for beginners. These printers usually cost between $5,000 and $15,000. They handle small to medium print jobs well. Brands like the Epson F2100 and Brother GTX fall into this category. They are reliable and produce good quality prints. Many new print shop owners start here.
Mid-Range Commercial Printers
Mid-range printers cost between $15,000 and $35,000. They offer faster print speeds and larger print areas. These machines are ideal for growing businesses. They handle higher volumes without breaking down. If you plan to take on regular orders, this tier makes sense.
Industrial-Grade DTG Systems
Industrial printers start around $35,000 and go up to $100,000 or more. These are for high-volume operations. They print hundreds of shirts per day. They also require more space and maintenance. Most new business owners do not need this level right away.
Understanding these price ranges helps you choose the right financing amount. You do not want to overpay or underinvest. Know your needs first.
Can I Finance A Dtg Printer? Yes, Here Are Your Options
Now let us answer the big question: can I finance a DTG printer? Absolutely. There are several financing paths available. Each one has pros and cons. Let us look at them all.
Equipment Loans
An equipment loan is a traditional loan specifically for buying machinery. The printer itself serves as collateral. This means the lender can repossess it if you default. Equipment loans usually have fixed interest rates and set repayment terms. Typical terms range from one to five years.
You own the printer from day one. Once you pay off the loan, the equipment is fully yours. This option works well if you have decent credit and want long-term ownership.
Equipment Leasing
Leasing is very popular in the print business startup world. Instead of buying the printer, you rent it for a set period. Monthly payments are usually lower than loan payments. At the end of the lease, you can buy the printer at a reduced price, return it, or upgrade to a new model.
Leasing is great for preserving business cash flow. You keep more money available for ink, apparel, and marketing. Many equipment financing companies offer lease-to-own programs that make this very flexible.
SBA Loans
The Small Business Administration offers loans with favorable terms. SBA 7(a) loans can cover equipment purchases up to $5 million. Interest rates are often lower than traditional business loans. The application process takes longer, but the benefits are worth it.
If you are a serious entrepreneur building a printing business plan, an SBA loan is worth pursuing. These loans are backed by the government, so lenders feel more confident approving them.
Retailer Financing Programs
Many DTG printer manufacturers and distributors offer their own financing. Companies like Epson, Kornit, and Brother sometimes partner with lenders to provide in-house payment plans. These programs can be very convenient. You buy the printer and set up payments in one place.
Watch out for promotional offers. Some retailers offer 0% interest for the first 12 months. But after that period, the rate can jump significantly. Always read the fine print.
Personal Loans and Credit Lines
If you are starting a home-based business, a personal loan might work. Banks and online lenders offer personal loans for business equipment. The approval process is usually fast. But personal loans often come with higher interest rates than business equipment loans.
A business credit line is another option. You draw funds as needed and pay interest only on what you use. This gives you flexibility. But again, rates may be higher than dedicated equipment financing.
How To Choose The Right Financing Option
Choosing the right financing option is not just about picking the lowest monthly payment. You need to think about the big picture. Here is what matters most.
Compare Total Cost of Ownership
Always look at the total amount you will pay over the life of the loan or lease. A lower monthly payment might mean you pay more in interest over time. Use a simple calculator to compare offers. Factor in interest, fees, and any buyout costs at the end.
Quick Tip: Ask the lender for a full amortization schedule. This shows you exactly how much interest you will pay over the entire term. It is the best way to compare options side by side.
Check Your Credit Score
Your credit score plays a huge role in what you qualify for. A score above 700 usually gets you the best rates. Scores between 600 and 700 still open doors, but expect higher interest. Below 600, you may need to look at alternative lenders or bring a co-signer.
Before applying, pull your credit report and fix any errors. Even a small improvement in your score can save you thousands of dollars over the life of a loan.
Consider Your Business Stage
Are you just starting out or already running a print shop? New businesses face more hurdles when getting approved for financing. Lenders want to see revenue history. If you are brand new, a lease might be easier to qualify for than a loan. Established businesses have more options available.
Think about your print business strategy too. If you plan to grow quickly, leasing lets you upgrade equipment as your business scales. If you want to build equity, a loan is the better path.
Pros and Cons of Financing a DTG Printer
Every financing option comes with trade-offs. Let us look at the big picture so you can decide what works best for you.
The Advantages
- Preserve your cash: You keep money in the bank for operations and emergencies.
- Build business credit: Regular payments improve your business credit profile over time.
- Start earning faster: You can begin printing and generating revenue right away.
- Tax benefits: Equipment loan interest and lease payments may be tax-deductible as business expenses.
- Upgrade flexibility: Leasing especially lets you move to newer technology without a huge upfront cost.
The Disadvantages
- Interest costs add up: You will pay more than the sticker price over time.
- Debt obligation: Monthly payments are a fixed expense that affects your business cash flow.
- Approval can be tough: New businesses without credit history may struggle to qualify.
- Equipment depreciation: Printers lose value over time, which matters if you want to sell later.
- Long-term commitment: Most financing terms last one to five years. You are locked in.
Comparison Table: Loan vs. Lease vs. Retailer Financing
| Feature | Equipment Loan | Equipment Lease | Retailer Financing |
|---|---|---|---|
| Ownership | Yes, immediately | At end of lease (usually) | Yes, immediately |
| Monthly Payment | Medium to High | Low to Medium | Varies |
| Term Length | 1-5 years | 2-5 years | 6 months – 5 years |
| Interest Rate | Fixed | Fixed or variable | Often promotional |
| Best For | Long-term ownership | Cash flow preservation | Quick and convenient setup |
| Credit Requirement | Good to excellent | Fair to good | Varies by retailer |
Common Mistakes To Avoid When Financing a DTG Printer
Many first-time buyers make avoidable mistakes. Learning from others’ errors can save you time and money. Here are the biggest pitfalls to watch out for.
Skipping the Business Plan
Some people jump straight into financing without a plan. Lenders will ask for a printing business plan. Without one, your chances of approval drop. A solid plan shows you understand your market, costs, and revenue projections. It also helps you figure out exactly how much equipment you can afford.
Ignoring Hidden Fees
The advertised rate is not always the real rate. Origination fees, early termination penalties, and maintenance fees can add hundreds or thousands of dollars. Always ask for a full breakdown of all costs before signing anything.
Over-Borrowing
Just because a lender approves you for a certain amount does not mean you should borrow it all. Stick to what you actually need. Overextending yourself creates pressure on your business cash flow and limits your ability to invest in other areas like marketing and inventory.
Not Reading the Fine Print
This one is critical. Always read every document carefully. Watch for clauses about balloon payments, rate adjustments, and early payoff penalties. If something does not make sense, ask the lender to explain it in plain language before you sign.
Expert Insight: “The biggest mistake we see is people choosing the lowest monthly payment without considering the total cost. A payment that looks great today can cost you much more over time,” says Mark Stevens, a business equipment advisor with over 15 years of experience in the printing industry.
Tips To Get Approved For DTG Printer Financing
Getting approved is not just about luck. You can improve your chances with a few smart moves. Here is what works.
- Check your credit score first: Know where you stand before applying. Fix any issues you find.
- Prepare a strong business plan: Include your market analysis, projected revenue, and expense breakdown.
- Show existing revenue: If you already have a business, provide bank statements and tax returns.
- Get pre-approved: Many lenders offer pre-approval without affecting your credit score. Use this to compare offers.
- Have a down payment ready: Even a small down payment shows lenders you are serious and reduces their risk.
- Work with a specialist: Equipment financing brokers understand the print industry. They can match you with the right lender.
These steps take a little effort but they pay off big time. You walk into the financing process prepared and confident.
Financing Alternatives To Consider
Financing is not the only way to get a DTG printer. If traditional loans do not work for you, consider these alternatives.
Buy Used or Refurbished Equipment
The used printing equipment market is booming. Many businesses sell their printers after upgrading. A refurbished DTG printer can cost 40-60% less than a new one. You still get good performance without the heavy price tag. Just make sure to buy from a reputable seller and get a warranty.
Start With a Heat Press Instead
Not sure a DTG printer is right for you yet? A heat press machine is much cheaper and easier to learn. You can start a t-shirt printing business with a heat press for under $1,000. Once your business grows, you can upgrade to a DTG printer using your profits.
Partner With a Print Shop
Another option is to partner with an existing print shop. You handle the design and sales while they handle production. This is called a dropshipping model for print businesses. You avoid equipment costs entirely and still earn money from custom apparel orders.
Crowdfunding and Grants
Small business grants and crowdfunding platforms can also help fund your print shop equipment. Some organizations offer grants specifically for minority-owned or veteran-owned businesses. Do your research and apply to as many as you qualify for. Every dollar you get for free is money you do not have to repay.
What Happens After You Finance Your DTG Printer
Once your financing is approved and the printer arrives, the real work begins. Setting up your print shop properly from day one sets you up for success.
Set Up Your Production Space
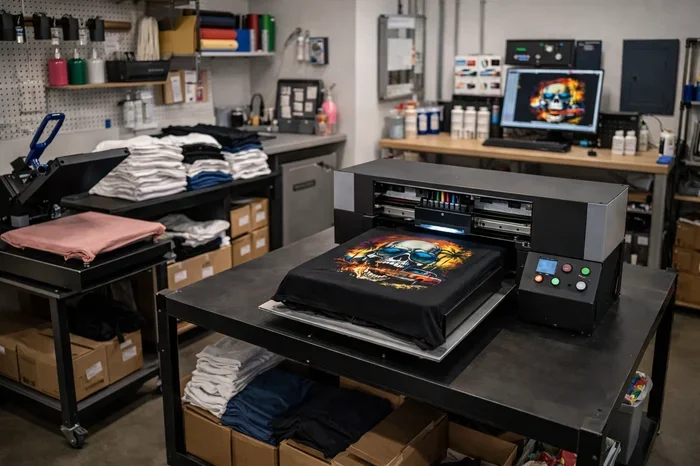
DTG printers need proper ventilation, stable power, and enough space to handle garments. Plan your layout carefully. Keep ink supplies organized and within easy reach. A clean, well-organized workspace improves print quality and speeds up production.
Invest in Quality Consumables
The printer is only one part of the equation. You also need premium pretreat, inks, and blank garments. Cutting corners on supplies hurts your print quality. Customers notice. Invest in good materials and your results will speak for themselves.
Build Your Marketing Strategy
Having a printer means nothing if nobody knows about your business. Use social media, local marketing, and online platforms to find customers. Consider print on demand services where you print only after receiving orders. This reduces inventory risk and keeps your business cash flow healthy.
Track Your Finances
Keep careful records of every payment, every order, and every expense. Understanding your numbers helps you see how fast you are paying off the equipment. It also helps you plan for future growth. Many print business owners use simple accounting software to stay on top of their finances.
Common Mistakes: Do not ignore your finances after the excitement of getting the printer wears off. The first six months are critical. Stay disciplined with your budget and your payments.
Final Thoughts: Taking The Leap With DTG Printer Financing
So, can I finance a DTG printer? The answer is a clear yes. Whether you choose an equipment loan, a lease, an SBA loan, or a retailer financing plan, you have real paths to getting the garment printing equipment you need. The key is to go in prepared. Know your budget, check your credit, and compare your options carefully.
Financing a DTG printer is not just about buying a machine. It is an investment in your print business startup or your existing operation. Done right, it lets you start earning revenue immediately while spreading costs over time. The print on demand business model is thriving, and having your own printer puts you in control of your growth.
Take your time. Do the research. Talk to lenders, compare offers, and choose the option that fits your situation best. The right financing decision today can set you up for years of success in the custom printing industry.
Frequently Asked Questions
What is the cheapest way to finance a DTG printer?
The cheapest way is usually an SBA loan or a low-interest equipment loan from a credit union. These options offer the lowest rates and longest repayment terms. Always compare the total cost, not just the monthly payment, to find the true cheapest option.
Can I finance a DTG printer with bad credit?
Yes, but your options will be more limited. Some equipment financing companies specialize in bad credit loans. Expect higher interest rates and possibly a larger down payment. Leasing may also be easier to qualify for with a lower credit score.
How long does DTG printer financing approval take?
It depends on the lender. Retailer financing programs can approve you in hours or days. SBA loans take several weeks because of the paperwork involved. Equipment loans from banks typically take one to two weeks for a decision.
Should I lease or buy a DTG printer?
If you want long-term ownership and equity, buying with a loan is better. If you need lower monthly payments and flexibility to upgrade, leasing is the smarter choice. Consider your cash flow, business stage, and how long you plan to use the printer before deciding.
Can I use a personal loan to buy a DTG printer?
Yes, you can use a personal loan for equipment. However, personal loans often have higher interest rates than business equipment loans. They also do not help you build business credit. If possible, explore business-specific financing first.
What other costs should I budget for besides the printer?
Beyond the printer, budget for ink, pretreat, blank garments, a heat press, a computer with design software, and marketing costs. A realistic startup budget for a small DTG print shop should include $2,000 to $5,000 in additional supplies and equipment.
=== CONCLUSION ===
Financing a DTG printer is one of the smartest moves you can make for your print business. The industry is booming, and demand for custom printed apparel continues to grow. Whether you are starting from scratch or expanding an existing shop, the right financing option puts professional-grade direct-to-garment printing equipment within your reach.
Remember to compare all your options. Look at total costs, not just monthly payments. Build a strong printing business plan. And take your time making the decision. The more prepared you are, the smoother the process will be.
Now that you know the answer to can I finance a DTG printer, it is time to take action. Research lenders, explore lease options, and find the financing path that fits your goals. Your print business is waiting to be built. Start today and watch your hard work pay off.